Refinancing your mortgage is one of the most powerful financial strategies available to homeowners today. Whether your primary goal is to lower your monthly payments, shorten your remaining loan duration, or cash out a portion of your accumulated home equity for major renovations, refinancing can save you tens of thousands of dollars over the lifetime of your property loan.
However, refinancing is not a one-size-fits-all financial trick. It involves replacing your existing mortgage with an entirely new loan agreement, complete with fresh underwriting criteria, closing costs, and updated terms.
If you are evaluating whether now is the right moment to refinance your home loan, this comprehensive step-by-step guide walks you through the entire process—from initial financial self-assessment to closing day.
1. Define Your Primary Refinancing Objective
Before reaching out to loan officers or gathering financial paperwork, you must clearly define why you want to refinance. Your specific objective determines the structure of the loan you should pursue:
- Securing a Lower Interest Rate: If prevailing market rates have dropped significantly since you originally purchased your property, refinancing can dramatically reduce your monthly interest burden.
- Shortening Your Loan Duration: Replacing a 30-year fixed mortgage with a 15-year structure allows you to eliminate your home debt in half the time while saving massive amounts in cumulative interest.
- Reducing Monthly Outlays: Resetting your remaining loan balance over a fresh 30-year schedule lowers mandatory monthly payments, providing vital cash flow flexibility for everyday living expenses.
- Executing a Cash-Out Refinance: Tapping into accumulated equity allows you to borrow a lump sum above your remaining mortgage balance for high-return uses like property upgrades, business investments, or high-interest debt consolidation.
- Eliminating Private Mortgage Insurance (PMI): If your home value has appreciated and your loan-to-value (LTV) ratio drops below 80%, refinancing enables you to remove costly monthly mortgage insurance premiums permanently.
2. Evaluate Your Financial Health and Credit Profile
Just as when you secured your original home loan, mortgage underwriters will thoroughly assess your current financial stability before approving a refinance application:
- Credit Score Standards: Most conventional mortgage lenders look for a minimum credit score of 620 for standard refinancing programs. However, scores above 740 unlock the most competitive interest rates on the market.
- Debt-to-Income (DTI) Ratios: Lenders analyze what percentage of your gross monthly income goes toward recurring debt obligations. Aim to keep your total DTI below 36% to 43% to ensure swift approval. If you want a refresher on how lenders calculate debt metrics, explore our detailed analysis of the debt-to-income ratio for homebuyers.
- Home Equity Stake: Lenders generally prefer that homeowners maintain at least a 20% equity buffer after refinancing. Holding less than 20% equity often triggers mandatory mortgage insurance requirements on the new loan.
3. Calculate Your Break-Even Timeline
Refinancing requires upfront capital outlays. Just like an initial home purchase, refinancing incurs closing fees—typically ranging from 2% to 6% of the new mortgage total.
To establish whether refinancing makes practical economic sense, you must calculate your break-even point—the exact duration (in months) required for your monthly payment savings to surpass total closing expenses.
The Break-Even Formula
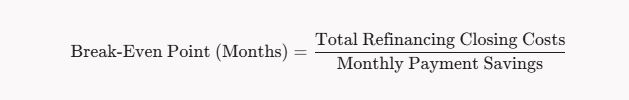
Real-World Scenario: Suppose your total refinancing closing costs equal $4,800, and your new lower interest rate reduces your monthly payment by $200. Your break-even calculation is:
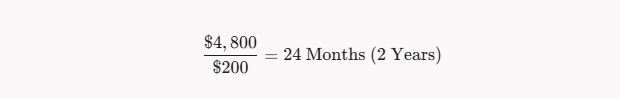
If you intend to remain in your home for more than 2 years, refinancing delivers genuine long-term net savings. However, if you plan to sell or relocate within 18 months, upfront transaction fees will swallow your monthly gains. Before choosing loan terms, compare financing mechanics in our guide on fixed-rate vs. adjustable-rate mortgages.
4. The 6-Step Mortgage Refinancing Process
Once you determine that the numbers work in your favor, follow these 6 structured steps to guide your refinance application through to funding:
Step 1: Compare Multiple Lender Quotes
Never sign with your current mortgage servicer without shopping around first. Obtain Loan Estimates from at least three to five competing institutions, including credit unions, digital lenders, and traditional banks. Small differences in interest rates and origination fees translate into huge savings over time.
Step 2: Assemble Complete Financial Documentation
Lenders demand up-to-date documentation to verify your employment, income stability, and asset balances. Gather these items beforehand:
- Recent pay stubs (last 30 to 60 days)
- W-2 forms and federal tax returns (last 2 consecutive years)
- Bank and investment account statements
- Current mortgage statements and property insurance documentation
Step 3: Lock In Your Interest Rate
Mortgage rates move continuously based on economic data and bond markets. Once you identify a competitive lender quote, request a formal rate lock. A rate lock guarantees your quoted interest rate for a specific window (usually 30 to 60 days) while your application goes through processing.
Step 4: Complete the Property Appraisal
Your lender will schedule a certified appraisal to confirm your property’s current fair market value. Ensure your home is clean, well-maintained, and accessible on appraisal day to maximize your valuation. Concurrently, underwriting officers review title histories and employment records.
Step 5: Budget for Closing Costs
Ensure you have liquid reserves prepared to handle closing fees on settlement day. If you want to review strategies for managing unexpected real estate transaction costs, check our comprehensive guide on how to budget for hidden closing costs when buying a home.
Step 6: Execute Closing Documents
At the closing table, you will review final disclosures, sign your new loan paperwork, and cover any remaining transaction balances. Following a mandatory 3-day right-of-rescission waiting period for primary residences, your new mortgage takes effect and fully pays off your previous loan balance.
5. Decision Matrix: Refinance Readiness
| Evaluation Metric | Ideal Refinancing Candidate | Pause & Re-Evaluate |
| Credit Score | 720+ (Secures top-tier pricing) | Below 620 (High pricing adjustments) |
| Home Equity | 20% or higher accumulated equity | Less than 10% home equity |
| Planned Occupancy | Staying well past the break-even date | Planning to move within 12-24 months |
| Interest Rate Gap | 0.75% to 1.5% lower than current rate | Rates equal to or higher than current rate |
| Primary Goal | Interest reduction / accelerated equity | High-risk short-term spending cash-outs |
Final Thoughts
Refinancing your mortgage is an effective tool to restructure debt, reduce monthly financial stress, and accelerate long-term net worth accumulation. By defining your goals clearly, verifying your credit metrics, calculating your break-even horizon, and comparing competitive lender proposals, you can execute a refinancing plan that strengthens your overall financial roadmap.
Take time to run your numbers, consult trusted mortgage professionals, and select the refinancing path that delivers maximum value to your home asset.