Introduction: Why Real Estate Math Is Your Shield Against Bad Deals
When I analyzed my first prospective rental property, I remember staring at the real estate agent’s glossy brochure. The listing claimed the property had an “unmissable cash flow potential” and promised an effortless passive income stream. It looked fantastic on paper—until I pulled out a blank spreadsheet and started calculating the actual operational expenses.
Within fifteen minutes of running real, conservative numbers, that “dream property” turned out to be a monthly cash-draining liability.
That single experience taught me the most fundamental lesson in real estate investing: never buy a property based on someone else’s marketing claims or your own emotional excitement.
The real estate market in 2026 demands a disciplined, mathematical approach. Rising property insurance premiums, shifting interest rates, and evolving tenant expectations leave no room for guesswork. Knowing how to calculate return on investment (ROI) accurately is the difference between building lasting wealth and taking on an expensive financial burden.
This guide walks through every step of evaluating rental property returns. We will break down key metrics—from Net Operating Income (NOI) to Cash-on-Cash Return—using a complete, real-world case study so you can run numbers with total confidence.
The Core Foundations: Income vs. Expenses
Before diving into complex formulas, you must organize your property’s cash flow into two distinct buckets: Gross Income and True Operating Expenses.
- Gross Annual Rental Income
- Minus Vacancy & Credit Loss Buffer
- = Effective Gross Income (EGI)
- Minus Operating Expenses (Taxes, Insurance, Property Management, CapEx Reserves, Maintenance)
- = Net Operating Income (NOI)
- Minus Annual Mortgage Payments (Principal + Interest)
- = Net Annual Cash Flow
1. Calculating Effective Gross Income (EGI)
Gross income is not simply Monthly Rent x 12. Assuming 100% occupancy every day of the year is a costly mistake.
- Gross Potential Rent: The total annual rent if the unit is occupied 365 days a year.
- Vacancy & Credit Loss Buffer: Always subtract 5% to 8% for potential vacancy between tenants or uncollected rent.
- Additional Income: Add recurring non-rent income, such as garage rentals, laundry facilities, or storage fees.
2. Estimating True Operating Expenses
Novice investors often forget hidden property expenses. A realistic budget must account for:
- Property Taxes: Check county assessment records rather than relying on current owner payments, as reassessments often occur after a sale.
- Property Insurance: Factor in regional rate adjustments and policy requirements.
- Property Management Fees: Even if you plan to self-manage initially, budget 8% to 10% of gross rent for professional management. This keeps your underwriting realistic if you decide to step back later.
- Repairs & Maintenance: Set aside 5% to 8% annually for ongoing wear-and-tear items like plumbing fixes, painting, and lock updates.
- Capital Expenditures (CapEx): Set aside 5% to 10% specifically for major structural replacements, such as roofs, HVAC units, water heaters, and appliances.
- Utilities: Include any utilities paid directly by the landlord (e.g., water, trash, or common-area electricity).
The 3 Must-Know ROI Metrics
Evaluating a property through a single lens is like driving a car while looking through only one mirror. To get a complete financial picture, calculate these three essential metrics for every deal.
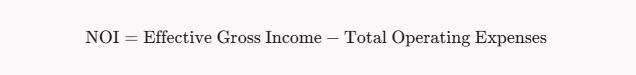
Metric 1: Net Operating Income (NOI)
Net Operating Income measures a property’s raw ability to generate cash purely from its operations, before factoring in debt (mortgages) or personal income tax situations.
The Formula:
Why It Matters:
NOI reveals how efficiently the property operates as a standalone asset. It allows you to compare two different properties fairly, regardless of whether one owner bought with cash and another used a high-interest mortgage.
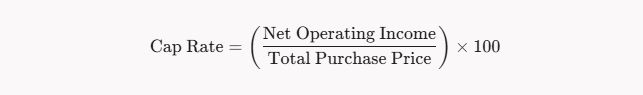
Metric 2: Capitalization Rate (Cap Rate)
The Capitalization Rate calculates the natural, unleveraged rate of return an asset produces. It answers a simple question: If I paid 100% cash for this property today, what percentage return would I receive each year?
The Formula:
Understanding Market Cap Rates:
- Higher Cap Rates (8% – 12%): Typically found in lower-cost markets or older neighborhoods. They offer higher immediate cash flow returns but may carry higher tenant turnover risks and slower long-term appreciation.
- Lower Cap Rates (4% – 6%): Found in premium, high-demand metropolitan areas. While initial cash flow may be modest, these properties generally offer strong tenant demand and reliable long-term value appreciation.
Metric 3: Cash-on-Cash Return (CoCR)
Most real estate investors do not pay 100% cash; they use leverage through bank mortgages. Cash-on-Cash Return measures the actual cash return earned on the physical cash dollars invested out-of-pocket.
The Formula:
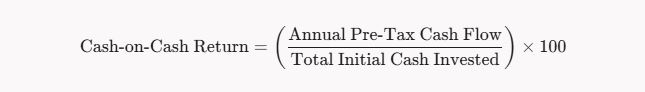
What Counts as “Total Initial Cash Invested”?
- Down Payment amount
- Lender origination fees and closing costs
- Initial inspection and appraisal fees
- Upfront repair or renovation costs required before tenant move-in
Real-World Case Study: Evaluating a $320,000 Single-Family Rental
To see how these formulas work together, let’s analyze a realistic scenario for a single-family home purchase.
The Purchase & Financing Terms:
- Purchase Price: $320,000
- Down Payment (20%): $64,000
- Closing Costs & Loan Fees: $8,000
- Initial Rehab / Prep Costs: $8,000
- Total Cash Invested Out-of-Pocket: $80,000
- Mortgage Amount: $256,000 at 6.8% interest (30-year fixed)
- Annual Mortgage Debt Service (P&I): $19,992 ($1,666 / month)
Annual Income & Expense Breakdown:
| Line Item | Monthly Amount | Annual Amount | Notes / Calculation |
| Gross Rental Income | $2,600 | $31,200 | Market competitive rate |
| Less: Vacancy Buffer (5%) | -$130 | -$1,560 | Safety reserve |
| Effective Gross Income (EGI) | $2,470 | $29,640 | Real collected income |
| Property Taxes | -$320 | -$3,840 | Local county rate |
| Property Insurance | -$125 | -$1,500 | Standard landlord policy |
| Property Management (8%) | -$198 | -$2,371 | Professional management |
| Maintenance & Repairs (6%) | -$148 | -$1,778 | Ongoing repair allocation |
| CapEx Reserves (6%) | -$148 | -$1,778 | Structural reserve allocation |
| Total Operating Expenses | -$939 | -$11,267 | 38% of EGI |
Calculating the 3 Key Metrics:
1. Net Operating Income (NOI):
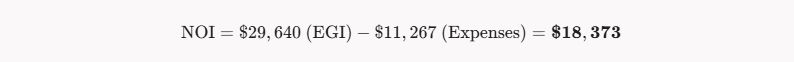
2. Capitalization Rate (Cap Rate):
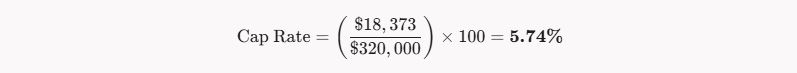
3. Cash-on-Cash Return (CoCR):
First, find the Annual Net Cash Flow after paying the mortgage:
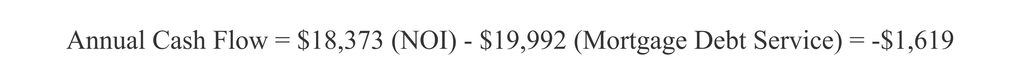
Next, calculate Cash-on-Cash Return:
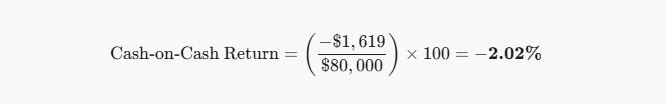
Analysis Verdict:
At a $320,000 purchase price with 20% down at a 6.8% interest rate, this property produces negative cash flow (-$135 per month).
To turn this deal into a positive investment, the buyer must:
- Negotiate a lower purchase price.
- Increase initial down payment capital to reduce mortgage payments.
- Identify low-cost property improvements that increase monthly market rent.
Without running these exact numbers first, a novice buyer might have focused only on the $2,600 rent check and bought a cash-losing property.
Advanced ROI Factors: Total Return on Investment
While Cash-on-Cash return shows immediate annual income, real estate offers four distinct wealth generation engines simultaneously:
- 1. Net Cash Flow: Monthly income remaining after operating expenses and debt payments.
- 2. Equity Paydown: Tenants steadily paying down your mortgage principal each month.
- 3. Market Appreciation: Long-term natural growth in property and land values.
- 4. Tax Benefits: Non-cash depreciation write-offs and tax-deductible operational expenses.
1. Principal Reduction (Equity Paydown)
Every month your tenant pays rent, a portion of your mortgage payment goes directly toward paying down the loan balance. Over time, this builds wealth silently—even if the market value of the property stays flat.
2. Long-Term Property Appreciation
While you should never buy a property solely on speculation, historic real estate values generally track or beat inflation over 10 to 20-year horizons.
3. Tax Benefits & Depreciation
In many tax jurisdictions, real estate owners can deduct property depreciation against rental income. Non-cash deductions often allow investors to shelter a significant portion of their physical cash flow from income taxes.
5 Rules of Thumb Every Beginner Investor Needs
- The 50% Rule: On average, operating expenses (excluding mortgage payments) tend to consume roughly 45% to 50% of gross income over the life of a property. Use this for quick back-of-the-napkin screening before running detailed numbers.
- The 1% Rule: A property should ideally rent for at least 1% of its total purchase price per month (e.g., a $200,000 home renting for $2,000/month). In higher-value markets, this ratio may hover closer to 0.7%–0.8%.
- Always Maintain Liquid Reserves: Keep at least 3 to 6 months of mortgage payments (PITI) stored safely in a high-yield account for each property to handle unexpected vacancies or emergency repairs.
- Never Ignore Local Reassessments: Property taxes often increase significantly following a property sale. Always compute returns using post-sale tax rates.
- Beware of “Pro Forma” Figures: Sellers and agents often present “Pro Forma” income statements based on ideal conditions. Always replace those figures with real, conservative market data.
Frequently Asked Questions
What is considered a “good” Cash-on-Cash Return for rental properties?
Most experienced investors look for a Cash-on-Cash Return between 7% and 12%. However, target returns depend on your strategy: investors in high-appreciation markets may accept 4%–6%, while investors in higher-risk markets typically target 10%+ returns.
How does Cap Rate differ from Cash-on-Cash Return?
Cap Rate measures property performance without considering debt (as if bought with 100% cash). Cash-on-Cash Return measures the specific return on your actual out-of-pocket cash investment, taking mortgage payments into account.
Should I include property appreciation in my initial ROI calculation?
It is safer to exclude market appreciation from your core cash flow calculations. Treat appreciation as a long-term bonus rather than a guaranteed monthly income source. Base your buying decision on current, verifiable income and expenses.
Final Thoughts
Calculating return on investment is not about finding trick shortcuts; it is about building a disciplined habit of analyzing deals objectively.
By calculating Net Operating Income, Cap Rate, and Cash-on-Cash Return on every prospective property, you remove emotion from your buying decisions. Use conservative estimates, budget for unexpected expenses, and let cold, hard numbers guide your path toward long-term financial independence.